More About Kai-Zen™
Blog
Before Year-End, Get Your Financial Plan on One Page
You may know what is in your retirement account. You may know what the business earned this year. You probably know the mortgage payment and what your family spends each month.
But could you explain how those numbers work together?
For many executives and business owners, the information exists in separate places. Investment statements are in one folder. Insurance documents are somewhere else. The CPA has the tax information. Upcoming expenses are still in your head.
October is a useful time to bring those pieces together. There is still time to ask questions, coordinate with your advisors, and decide what deserves attention before the year ends.
Start with a one-page financial summary.
It will not replace a complete financial plan. It can help you see what needs a closer look.
Start With What Your Money Needs to Do
Before listing accounts and balances, write down your most important financial priorities.
Perhaps retirement is getting closer. A child will begin college next year. The business needs additional working capital. You want to support your church more consistently or make sure your spouse has greater financial security.
Be specific enough that the goal can guide a decision.
“Prepare for retirement” is a starting point. “Understand whether retiring in five years is realistic” gives the review a clearer purpose.
Choose three priorities for the next twelve months. Those priorities will help you decide where available money and attention should go.
Separate Dependable Income From Variable Income
A strong earnings year can make a financial commitment feel comfortable. That same commitment may feel different when a bonus is smaller or business distributions decline.
List your dependable income separately from income that varies.
For an executive, that might mean separating salary from bonuses and stock compensation. For a business owner, it may mean distinguishing regular compensation from distributions that depend on company performance.
Then identify the obligations that continue regardless of how the year turns out:
Household living expenses.
Debt payments.
Insurance premiums.
Existing savings and funding commitments.
Expected tax payments.
The question is straightforward:
Can dependable income support your ongoing commitments, or does the plan require a strong year every year?
If variable income is covering essential expenses, that is worth discussing before adding another obligation.
Show What You Own and What You Owe
Next, list your major assets and debts using approximate current values.
Include cash, retirement accounts, other investments, real estate, and business ownership interests. Alongside them, record mortgages, personal loans, and relevant business obligations.
For business owners, keep company assets and household assets clearly separated. A valuable business can be an important part of your financial future, but its estimated value does not tell you how much money is available for personal spending.
Also distinguish money you can access readily from assets that may take time to sell or have restrictions.
That distinction matters when an opportunity, expense, or emergency arrives.
Identify Cash You Will Need Soon
Look ahead over the next twelve months.
Are there tuition payments, home repairs, medical expenses, tax payments, or business investments coming up? Is retirement, a job change, or a major purchase approaching?
Write down the expected amount, timing, and likely funding source for each significant expense.
If the funding source is unclear, you have found a planning question.
If the same money is assigned to several purposes, you have found another.
For example, a bonus cannot fully fund a business expansion, a household reserve, and a new long-term strategy at the same time. Seeing those competing uses on one page helps you choose deliberately.
Include Protection and Important Documents
A financial summary should also identify the arrangements that protect your household.
Note your existing life and disability insurance, whether coverage depends on your employer, and when it was last reviewed. Record whether beneficiary designations and estate documents reflect your current circumstances.
You do not need to put every policy provision or legal detail on the page. Identify what exists, where the documents are stored, and what needs review.
This becomes especially useful after a job change, business transition, marriage, divorce, or change in family responsibilities.
Give Every Strategy a Clear Role
Once you understand your position, you can evaluate whether an additional strategy belongs in the plan.
That might involve adjusting retirement contributions, reviewing investment allocation, updating insurance, or exploring a strategy such as Kai-Zen.
Start by identifying the need it would address.
Then ask how the proposed commitment affects available cash, existing obligations, and longer-term goals. Understand the costs, risks, funding requirements, and access restrictions before making a decision.
A strategy deserves consideration when its role is clear and its commitments fit your circumstances.
Choose Three Next Steps
The review may reveal several issues. Trying to resolve all of them at once can make it harder to move forward.
Choose three actions based on their importance, timing, and effect on the rest of your finances.
Your next steps might be:
Ask your CPA to update your estimated tax position.
Review whether current retirement funding supports your intended retirement date.
Clarify how much cash should remain available for household and business needs.
For each action, write down who will handle it and the next date to check progress.
Confirm the actual deadline with the appropriate professional or plan provider. Some actions are tied to year-end; others follow different schedules.
Make the Next Conversation More Useful
You do not need a perfect spreadsheet to begin.
A clear summary of your priorities, income, assets, obligations, and upcoming needs can make your next planning conversation more productive.
It gives you and your advisors a shared starting point. It also helps reveal whether a decision in one area could create a problem somewhere else.
Before the year gets busier, put the important pieces on one page.
Then ask:
What needs to change so these pieces support the future you are planning for?
Book a Clarity Call with Cornell Financial Group to discuss your priorities and the questions your year-end review brings into focus.
The Strange Lie The Church Is Starting To Believe
In “The Strange Lie The Church Is Starting To Believe,” the message raises an important concern about how some churches and Christians may be slowly accepting ideas that sound good but do not fully align with what the Bible teaches. It reminds us that not everything presented as spiritual truth necessarily comes from God’s Word. As society changes, there can be pressure to make Christianity more comfortable, avoid difficult biblical teachings, or follow what is popular rather than what Scripture says. The message encourages believers to examine what they hear, understand the Bible for themselves, and recognize the difference between genuine faith and teachings that may lead them away from the truth.
What really stands out is the reminder that following Jesus is not about changing God's Word to fit our lives, but allowing God's Word to change how we live. We are encouraged not to accept every teaching simply because it comes from a church or a well-known speaker. Instead, we should stay grounded in Scripture, pray for discernment, and remain faithful to Christ even when biblical truth is unpopular. The central lesson is that a strong faith requires more than attending church or listening to sermons. It requires knowing God's Word, living by it, and having the courage to stand firm in what we believe.
Creating Tax Free Wealth For Business Owners
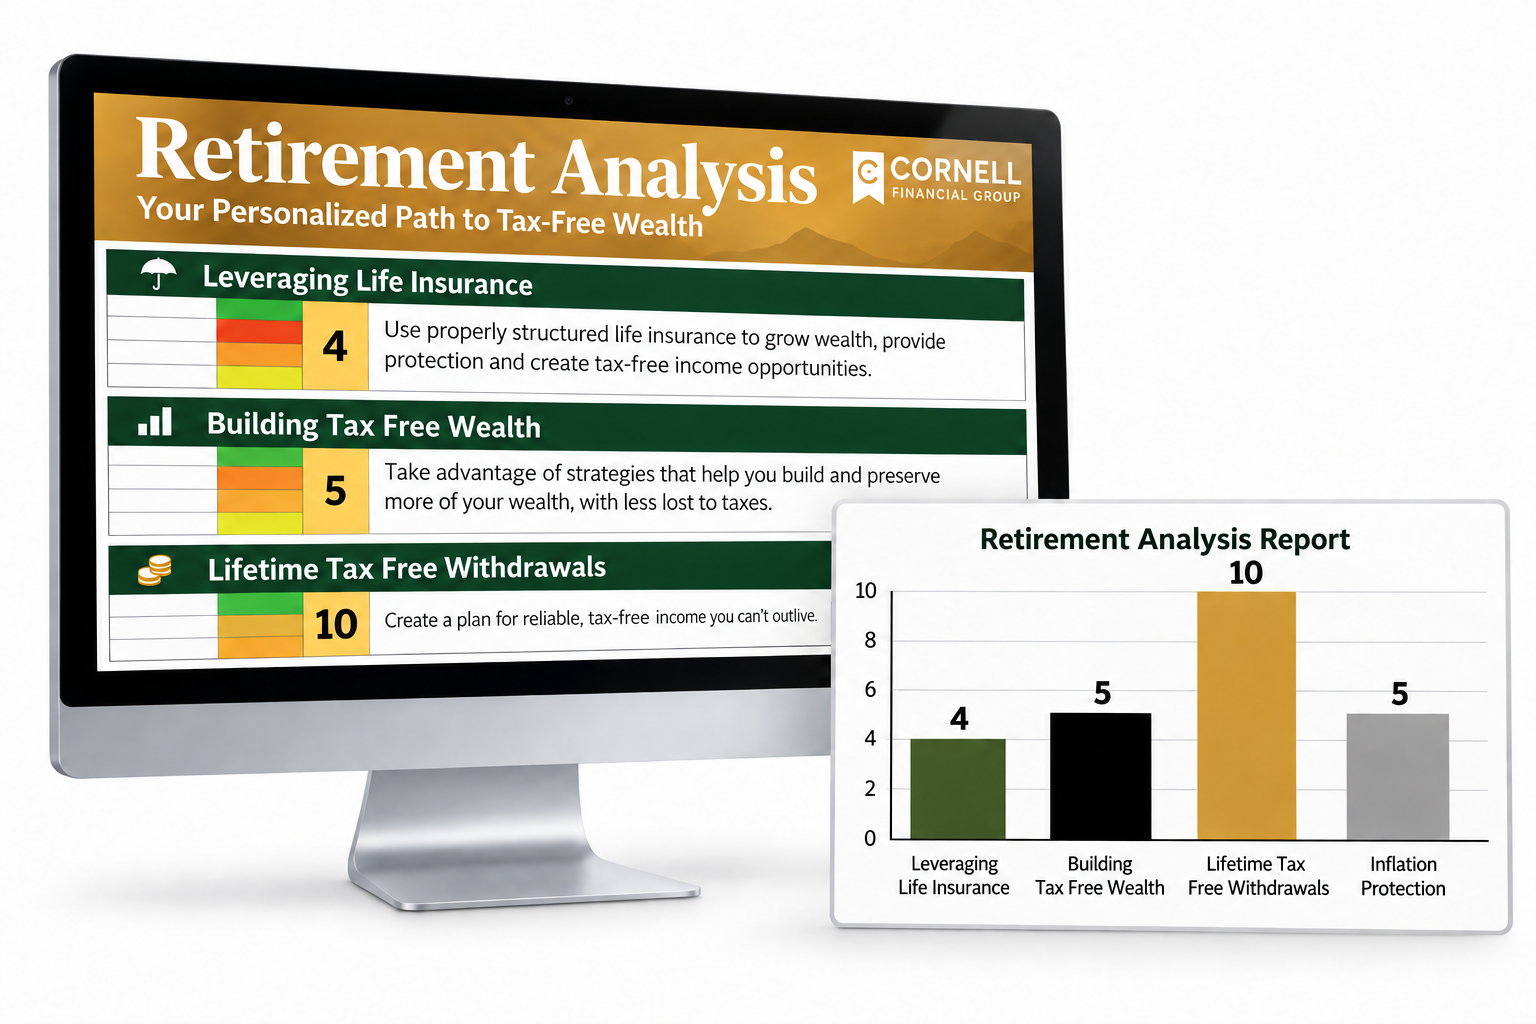
Kai-Zen was first introduced in 2012 by NIW. The underlying financial approach has been utilized by wealthy individuals and estates (typically $10M and over) since the 1960s. Kai-Zen is a new variation on this approach - allowing highly compensated individuals like yourself to participate in this type of leveraging for the first time.
Learn More About Kai-Zen™
Take Comfort in Understanding Your Strategy!
No one knows what will happen in the future but looking at the past uncovers some common patterns. Stressing our designs through some of the harshest economic conditions to date allows us to implement a strategy to help protect against potential future failures and optimizes our chances for a more successful outcome.
"Let us not become weary in doing good, for at the proper time we will reap a harvest if we do not give up."
- Galatians 6:9 (NIV)
Home
Our Story
Kai-Zen™
Resources Center
Unlock the path to tax-free wealth and watch your business flourish like never before.


An Independent Licensed Agent Representing NIW Companies, Inc. Creators of The Kai-Zen Plan
Cornell Financial Group © Copyright 2026 | All Rights Reserved